Your house is more than just a building. It carries with you your memories, your belongings, your everyday needs. Damage resulting from a fire, storm or sudden accident can quickly add up when it comes time to repair or replace. Depending on the type of homeowner’s policy, some financial losses can be covered by homeowners insurance.
If you are asking what does homeowners insurance cover, most policies will typically cover damage to your home and property, personal belongings, liability claims and some additional living expenses.
Here are 10 important things to understand before choosing or reviewing a policy.
1. Damage to Your Home’s Structure
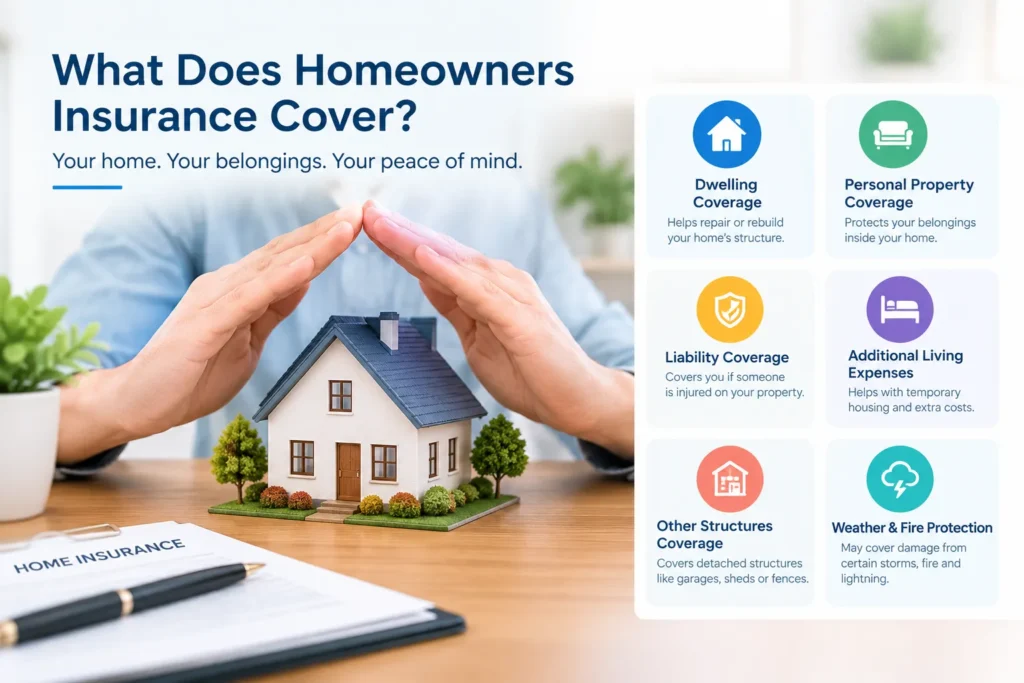
Dwelling coverage will help provide funds to rebuild or repair the physical structure of your home after a covered event. This can include roof, walls, floors and any related structure like a garage.
Fire, lightning, windstorm and some other damages that are sudden in nature are usually part of covered events. The level of protection will vary depending on your insurance.
The first step in knowing what does homeowners insurance cover is to determine if your dwelling coverage is adequate to cover rebuilding your home at today’s construction costs. Your home’s value in the marketplace does not necessarily equal its rebuilding cost.
2. Personal Belongings Inside Your Home
Personal property coverage guards against loss or damage to personal items like furniture, clothing, electronics, appliances and more, when damaged, destroyed or stolen in covered situations.
If a fire damages your furniture in the living room, for instance, your policy might cover the cost to replace the items you have, up to a limit and deductible.
When reviewing what is covered under homeowners insurance, check special limits for valuables such as jewelry, watches, artwork, and collectibles. High-dollar items might require special coverage or insurance policy.
3. Detached Structures on Your Property
Many homeowner’s policies will cover unattached structures. These can include a garage, garden shed, fence or gazebo that is separate from the house.
This coverage typically comes with its own cap, which is typically a percentage of your dwelling coverage. Review your policy to ensure that what is covered and your limits are adequate.
4. Additional Living Expenses
If your home becomes temporarily uninhabitable due to a covered loss, additional living expenses coverage can help cover some of these additional expenses.
For instance, if there’s been a big fire, you may have to live in a hotel or hire another apartment while your home is being repaired. This coverage can assist with an increase of housing, meal and other necessary living costs that may qualify for coverage.
Does not always cover all costs in times of displacement. Your policy may have caps on benefits amount and/or duration.
5. Personal Liability Protection
Personal liability coverage is included in homeowners insurance. If you are liable for another party’s accident and caused damage to a property, this may help to protect your finances.
For example, a patron could slip on your premises and claim medical costs or other damages.
Depending upon the situation, liability coverage could be used to help pay for covered legal costs and settlement.
Be sure to check your liability limits, especially if you have a swimming pool and/or host a lot of guests.
6. Medical Payments to Others
Minor injuries coverage is included for guests in some of the policies even if you are not liable. May pay eligible medical expenses, within the limits of the policy.
This coverage is typically provided for smaller claims, not big injury cases. Serious claims could be covered under personal liability if conditions are met.
7. Damage From Fire, Smoke, and Lightning
Standard homeowners policies include covered perils such as fire, smoke or lightning. A covered event can impact your structure and property, or both, depending on the circumstances.
Coverage is limited, however. Policy exclusion, maintenance problems, coverage limits and the cause of the damage can all impact a claim.
Reviewing your homeowners insurance coverage can help you understand which losses may be covered and what records you may need to present when filing a claim.
8. Certain Storm and Weather Damage
Some policies include protection from losses due to windstorm, hail and other specified weather events. Protection is however, not uniform by area and policy.
Typically, you must have separate flood insurance coverage for flooding, and earthquake damage is usually covered only if it is added to your policy. Additionally some policies have special wind or named storm deductibles.
If you live in an area with harsh weather conditions, check with your insurance company to find out what hazards are included and what might need extra coverage.
9. What Homeowners Insurance Does Not Cover
Understanding what homeowners insurance does not cover is just as important as knowing what it protects. Common exclusions or limitations may include:
- Flood damage: Usually requires separate flood insurance.
- Earthquake damage: Often excluded unless additional coverage applies.
- Wear and tear: Gradual deterioration and neglected maintenance are generally not covered.
- Pest damage: Termites and similar infestations are commonly excluded.
- Intentional damage: Deliberate damage is generally not insured.
- Certain mold damage: Coverage may depend on the cause and policy wording.
These are common examples, not universal rules. Some policies offer endorsements that broaden protection, so check your own policy for precise terms.
10. Temporary Repairs and Debris Removal
Homeowners insurance may be able to help cover reasonable temporary repairs in the aftermath of a covered event, depending on the policy and circumstances. May also include eligible debris removal.
For instance if a storm damages a roof, a temporary roof cover that is placed on the damaged area can help keep further water from entering the house. Save receipts, take pictures and get in touch with your insurance company as soon as possible.
Unless immediate action must be taken to protect persons or prevent further damage, don’t make permanent repairs without cataloguing damage and following your insurance company’s claims procedure.
Conclusion
Knowing what does homeowners insurance cover helps you prepare for unexpected damage and avoid surprises when filing a claim. Understanding your coverage before a loss occurs can make it easier to make informed decisions about protecting your home.
Frequently Asked Questions
What does home insurance cover in general?
Home insurance commonly protects the house, personal belongings, certain detached structures, and personal liability. It may also cover additional living expenses after a covered loss makes the home uninhabitable.
Does homeowners insurance cover roof damage?
It often covers sudden roof damage caused by a covered event, such as certain windstorms or hail. Damage from aging, deterioration, or neglected maintenance is generally excluded.
Does homeowners insurance cover stolen belongings?
Yes, personal property coverage may pay for eligible stolen belongings, subject to policy limits, deductibles, and exclusions.
Does homeowners insurance cover water damage?
Some sudden and accidental water damage may be covered. Flooding, gradual leaks, and maintenance-related problems may be excluded or require separate coverage.
Does homeowners insurance cover mold?
Coverage depends on the cause of the mold and the policy. Mold resulting from a covered event may receive limited protection, while mold caused by long-term moisture or neglect is often excluded.