Choosing home insurance is about more than finding the lowest price. Two policies may have similar premiums but offer very different levels of protection, coverage limits, and deductibles. Knowing how to compare home insurance options can help you find a policy that fits your property, budget, and needs.
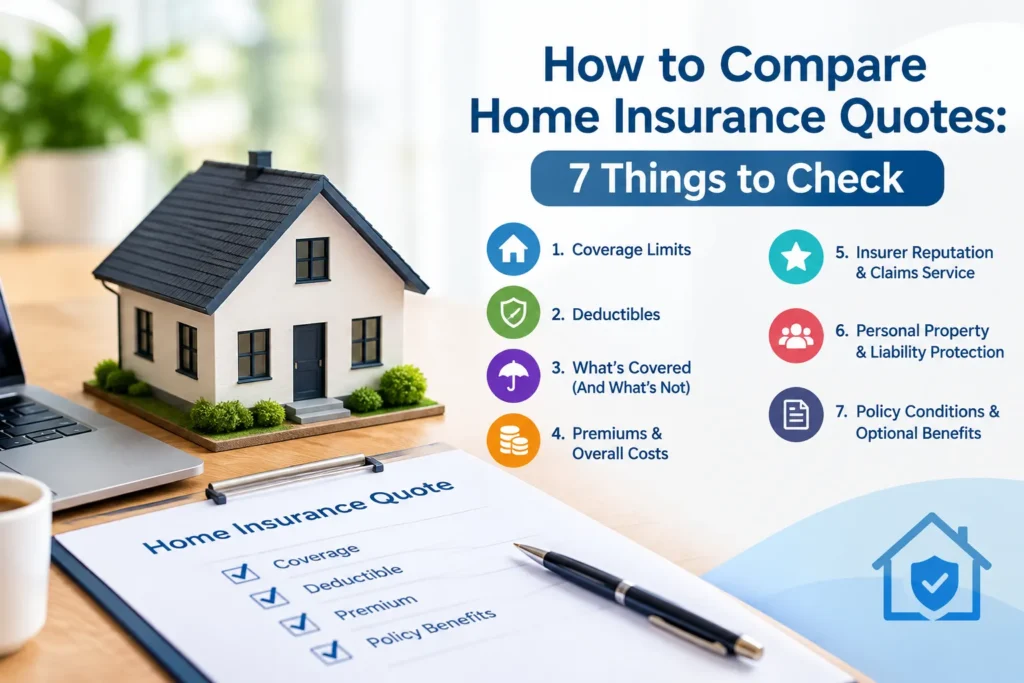
Before making a decision, review these seven important factors to understand what each insurer actually offers.
1. Compare Coverage Limits
Coverage limits determine how much your insurer may pay for a covered loss. Check the limits for your home’s structure, personal belongings, liability, and additional living expenses if your home becomes temporarily uninhabitable.
When learning how to compare home insurance quotes, make sure the policies provide similar protection. A cheaper quote may offer lower limits that leave you paying more out of pocket after a major loss.
2. Check Deductibles
A deductible is the amount you pay toward a covered claim before your insurance pays the remaining eligible costs. Some policies have separate deductibles for specific risks, such as wind or hurricanes.
A higher deductible can lower your premium, but it also means you must pay more when filing a claim. Choose an amount you could comfortably afford in an emergency.
3. Understand What Is and Isn’t Covered
Not every homeowners insurance policy covers the same risks. Standard policies may cover certain fire, theft, and storm-related losses, but flooding, earthquakes, and gradual wear and tear are often excluded or handled through separate coverage.
To compare home insurance policies accurately, review exclusions, special limits, and optional endorsements. If your home faces a particular risk, confirm whether additional coverage is available and whether it is necessary for your situation.
4. Compare Premiums and Overall Costs
The premium is the amount you pay for your insurance, usually monthly or annually. However, the lowest premium does not always represent the best value.
Consider the premium alongside deductibles, coverage limits, exclusions, and optional protection. Ask about discounts for security systems, smoke detectors, bundled policies, or other qualifying features.
When you compare homeowners insurance quotes, make sure each quote uses similar coverage levels and property details. Otherwise, you may be comparing different levels of protection rather than genuinely comparable prices.
5. Review the Insurer’s Reputation and Claims Service
Insurance is most valuable when you need to file a claim. Research each company’s financial strength, customer service, and claims-handling reputation.
Look for patterns in customer feedback, particularly regarding claim delays, communication, and settlement disputes. You can also check independent ratings and your state insurance department’s consumer resources.
A slightly higher premium may be worthwhile if the policy offers suitable protection and the insurer has a reliable claims process.
6. Check Personal Property and Liability Protection
Your home insurance should account for more than the building itself. Personal property coverage helps protect eligible belongings, while personal liability coverage may help with covered claims if you are legally responsible for someone else’s injury or property damage.
Review the limits for furniture, electronics, clothing, jewelry, and other valuables. Some expensive items may have special limits and require additional coverage.
If you’re deciding how to choose home insurance coverage, consider the value of your belongings, your household’s needs, and the potential financial impact of a liability claim.
7. Review Policy Conditions and Optional Benefits
Before choosing a policy, read the conditions that explain how coverage works. Check requirements for reporting damage, documenting belongings, maintaining the property, and notifying the insurer about significant changes.
Also compare optional benefits, such as water backup coverage, replacement-cost protection, or identity theft assistance, where available. Make sure you understand what each benefit covers and whether it justifies the extra cost.
These details can help you determine how to pick home insurance that offers practical protection instead of paying for features you do not need.
How Many Home Insurance Quotes Should I Get?
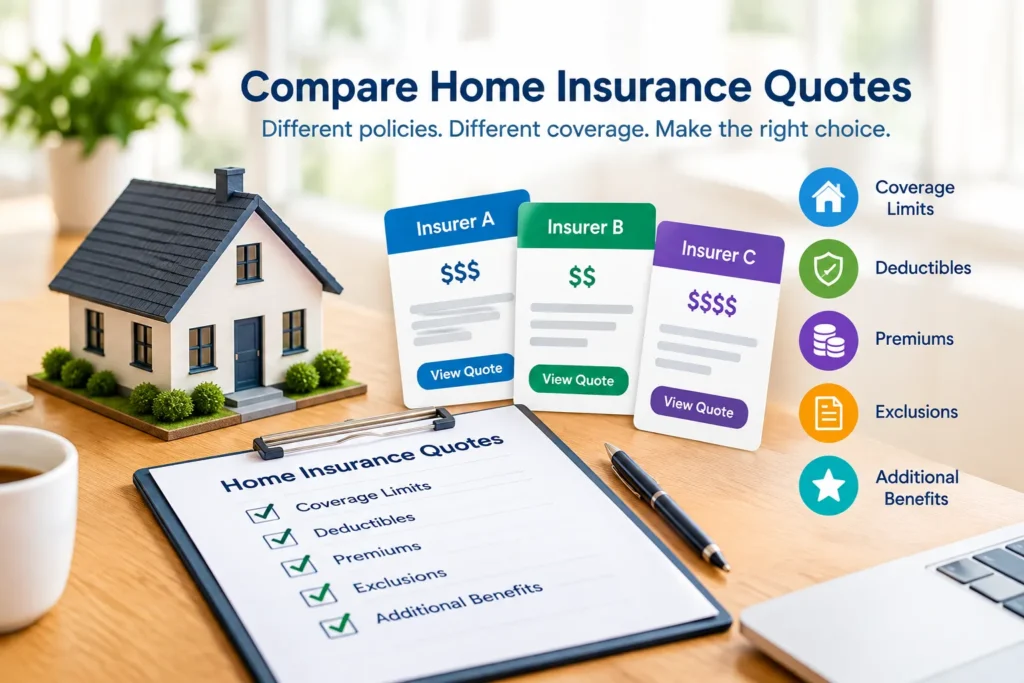
Most homeowners can start by obtaining three to five home insurance quotes from different insurers. This provides a useful range of prices and coverage options without making the comparison process unnecessarily complicated.
Try to provide the same property details, coverage limits, and deductible preferences to every insurer. This makes it easier to identify meaningful differences between policies.
If you’re unsure how to compare home insurance quotes, create a simple comparison sheet with each insurer’s premium, deductible, coverage limits, exclusions, and optional benefits. Review the details side by side before making your decision.
How to Choose Homeowners Insurance That Fits Your Needs
Knowing how to choose homeowners insurance begins with understanding what you need to protect. Consider your home’s rebuilding cost, the value of your possessions, your location’s risks, and how much you could afford to pay after a covered loss.
Do not base your decision on the home’s purchase price alone. Land value, construction costs, and other factors can affect the amount of dwelling coverage you need.
Ask questions whenever a policy term or exclusion is unclear. An insurance agent can explain available options, but you should review the actual policy documents before committing.
Conclusion:
Learning how to compare home insurance quotes helps you look beyond the price and understand what each policy provides. By checking coverage limits, deductibles, exclusions, insurer reputation, and policy conditions, you can make a more informed decision.
Start with three to five comparable quotes, review the policy documents carefully, and choose coverage that protects your home without stretching your budget.
Frequently Asked Questions
Is the cheapest home insurance quote the best option?
Not necessarily. A low premium may come with higher deductibles, lower coverage limits, or more exclusions. Compare the overall protection and cost before choosing.
How many home insurance quotes should I get?
Three to five quotes are a practical starting point. You can request more if the initial options do not provide suitable coverage or competitive pricing.
What is the difference between replacement cost and actual cash value?
Replacement cost generally pays the eligible cost of replacing covered property without deducting depreciation, subject to policy terms and limits. Actual cash value generally accounts for depreciation.
Should all home insurance quotes have the same deductible?
For a fair comparison, use the same deductible whenever possible. If deductibles differ, account for that difference when evaluating premiums.
Does home insurance cover flooding?
Standard homeowners policies often exclude flood damage. Separate flood insurance may be available through private insurers or government-backed programs, depending on your location.
Can I switch home insurance companies at any time?
In many cases, yes, but check your current policy’s cancellation terms and any mortgage-related insurance requirements. Avoid a gap in coverage when changing insurers.
What factors affect home insurance premiums?
Common factors include location, rebuilding cost, property age, roof condition, claims history, deductible, coverage limits, and selected endorsements.
How do I know how much dwelling coverage I need?
Estimate the cost to rebuild your home using current local construction costs rather than relying solely on its market value. An insurer or qualified professional may help you assess the appropriate amount.
Should I compare customer reviews when choosing an insurer?
Yes. Reviews can offer insight into communication and claims experiences, but consider them alongside financial-strength ratings, policy terms, and other reliable information.
What should I check before accepting a home insurance quote?
Review the premium, deductibles, coverage limits, exclusions, personal property protection, liability coverage, and policy conditions.